

Off-plan means buying a property from a developer before construction is complete, paying in instalments tied to booking and building milestones, and taking the keys when the building is finished. In Dubai it is not a niche. In most recent years, more than half of all residential sales registered with the Land Department have been off-plan, and in new districts the share is close to all of them.
That scale is why the mechanism is so well developed here. Every registered project must hold buyers' money in a project-specific escrow account regulated by RERA, and every contract is recorded on the Land Department's interim register, Oqood, in the buyer's name. Those two structures are covered in their own articles in this pillar; the point here is that they exist, and that they are what make off-plan a regulated purchase rather than a deposit on a promise.
What you are actually choosing
A resale buyer chooses a unit. They stand in it, see the view, open the cupboards and judge the neighbours' balconies. An off-plan buyer cannot do any of that, so the decision moves up a level. You are choosing a developer whose record you can check, a community whose stage of completion you can see, a payment structure you can afford through to handover, and a date that you accept may move.
The unit still matters — floor, orientation, layout, whether the view will survive the next tower — but it is chosen from a floor plate and a render, and it is chosen second. Most of the expensive mistakes we see come from buyers who chose the unit first and the developer last.
You are not buying an apartment. You are buying a developer's promise to build one, with a regulator standing between you and the developer's bank account.
How the money moves
A typical purchase starts with a booking deposit, usually 5% to 20% of the price, followed by the sale and purchase agreement and registration on Oqood, at which point the Land Department's transfer fee, currently 4%, is due. Further instalments follow the plan structure — 60/40, 80/20 and so on — with the first number paid during construction and the second at handover, or after it on a post-handover plan.
Every payment goes into the escrow account, and the developer can draw on it only against construction progress certified by an independent consultant. What you do not pay is a mortgage from day one, unless you choose to: most buyers fund the construction instalments from income or savings and arrange finance, if at all, for the handover payment.
What you get for the wait
The case for off-plan rests on three things. Entry prices are typically below the equivalent completed unit in the same district, because you are being paid for the wait and the risk. The payment is spread over years, which suits buyers who earn well but do not hold the whole price today. And you get a new building with a defects liability period, rather than a fifteen-year-old tower with rising service charges.
The case against it is equally clear. The date can move — a quarter or two is common, and longer delays happen. The finish may differ from the show apartment. The district around the building may take years longer than the building itself, so the first tenants live on a construction site. And if you need to exit before handover, the market for your contract depends on how the project is trading at that moment, not on what you paid.
When it is the wrong choice
Off-plan is wrong for anyone who needs to live in the property within the next year or two, for anyone whose finances cannot absorb a twelve-month delay in handover, and for anyone buying purely on a projected yield, because the yield does not exist until a tenant signs. It is also wrong, in our view, in a district where nothing has been delivered yet and the developer has no record — unless you are sizing the purchase as the bet it is.
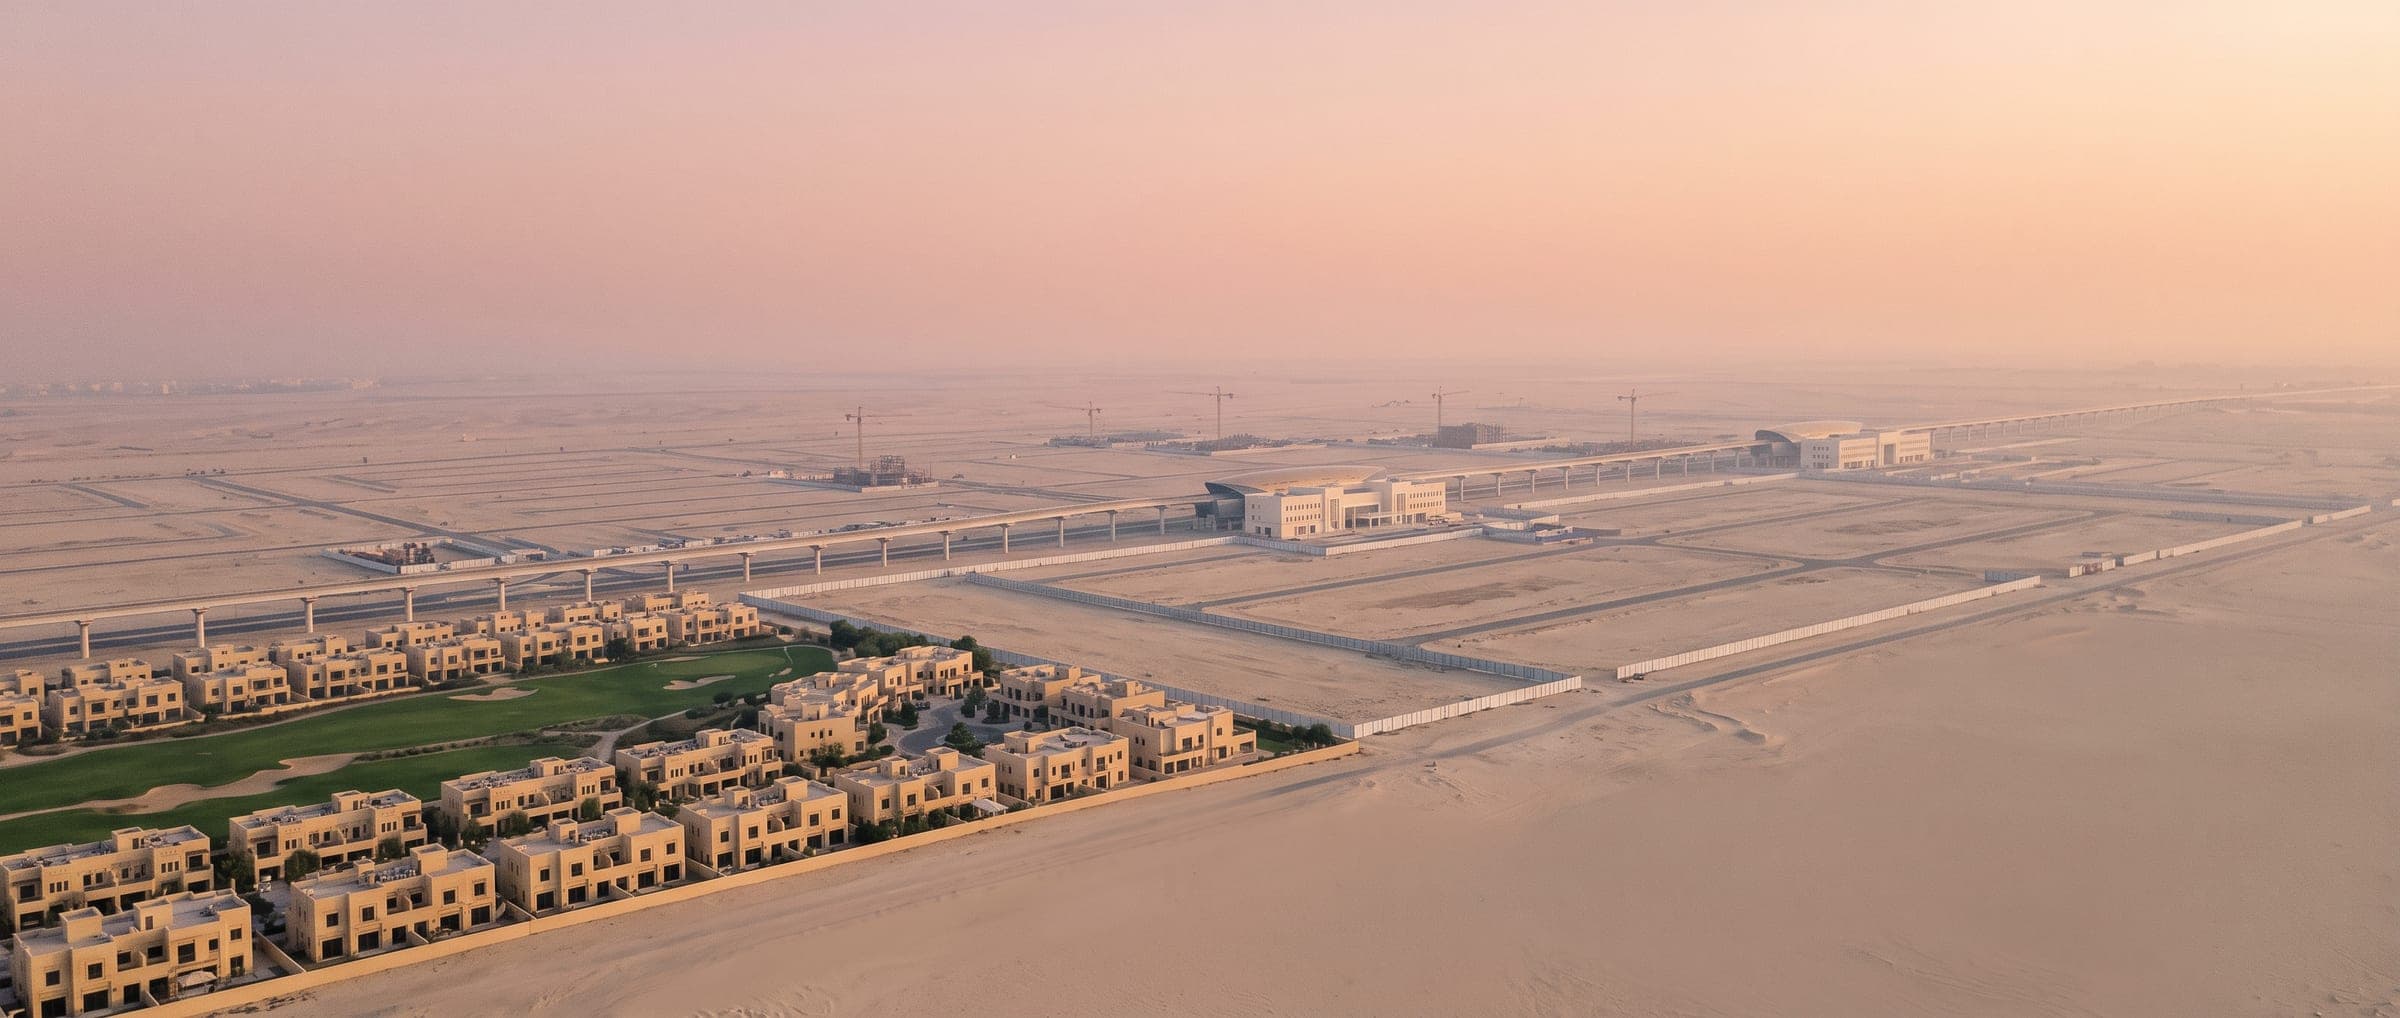
For everyone else, it is a well-regulated way to buy a new home or a new investment in a city that is still building itself. The rest of this pillar explains each part of the mechanism in turn, so that when a payment plan or an escrow account is mentioned in a conversation, you already know what it means and what to ask.